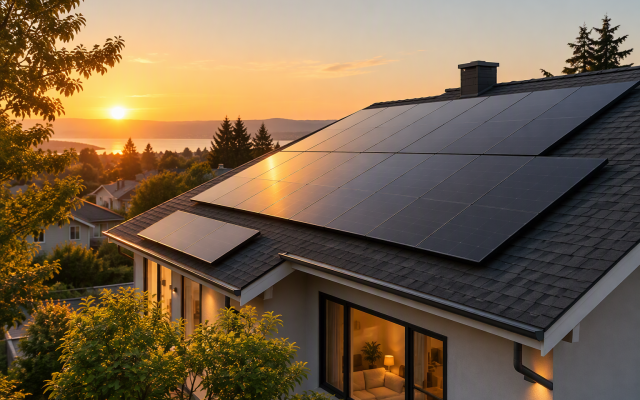
The US federal tax credit that paid 30 per cent of the cost of a residential solar system is no longer available for new installations. The Internal Revenue Service states the rule plainly on its own page: the credit “is not available for any property placed in service after December 31, 2025.”
That sentence is the whole change, and it is worth reading twice because most of the confusion around it comes from mixing two different questions — whether a system qualifies, and whether a taxpayer can still use a credit already earned.
What the credit covered
Section 25D, the residential clean energy credit, applied to qualifying equipment installed at a US home: solar electric panels, solar water heating, wind turbines, geothermal heat pumps, fuel cells and battery storage, subject to the conditions in the IRS guidance. The credit was 30 per cent of the qualified cost, and it was claimed on the taxpayer’s return for the year the property was placed in service — not the year the contract was signed, and not the year the deposit was paid.
“Placed in service” is therefore the operative phrase. A system is placed in service when it is installed and ready to produce, which for a rooftop array usually means after the utility has given permission to operate. A contract signed in December 2025 for a system energised in March 2026 does not qualify on the date of the signature; the IRS rule is about when the property was placed in service.
If the system went in during 2025
The credit is still available for a system placed in service on or before 31 December 2025, and it is claimed on that year’s return. Two mechanics matter for anyone filing now.
First, the credit is non-refundable: it reduces tax owed, and if the credit is larger than the tax liability in that year, the IRS allows the excess unused credit to be carried forward to later years. A household that installed an expensive system and owes modest tax may therefore still be claiming the credit years after the panels went up. Second, the credit is claimed on Form 5695, and the instructions for that form are the authority on which costs qualify — installation labour, wiring and permitting are typically part of the qualified cost, while a roof repair done at the same time is not.
The carryforward is also the reason a 2026 tax return can still show this credit. A credit carried forward from a 2025 installation is not a new credit for 2026 property; it is last year’s credit being used this year, and the distinction matters if a return is examined.
If the system goes in during 2026
There is no federal residential clean energy credit for a system placed in service after 31 December 2025. That changes the sales conversation more than it changes the engineering. A quote that presents a “30 per cent federal credit” as part of the net cost is applying a rule that ended; the honest version shows the gross price, then any state, local or utility programme the homeowner actually qualifies for, with the programme’s own conditions attached.
State and utility incentives are not uniform and several have their own sunset dates, caps and income tests. They should be verified with the programme administrator rather than inferred from a national map, and they are the first question to ask an installer now that the federal line has gone.
What has not changed
The physics has not changed, and neither has the arithmetic that decides whether a system pays for itself: the cost per installed watt, the local tariff, how much of the generation the household uses itself, and how the utility credits exports. Removing a 30 per cent credit lengthens the payback period for a cash buyer; it does not make the panel produce less. A household comparing quotes in 2026 is comparing gross prices and local incentives, and the calculation is more transparent for it, even if the number is worse.
The commercial rules are a separate matter and were not touched by the residential change in the same way; a business or a landlord evaluating a project should look at the commercial credits with an adviser rather than carry a residential rule across.
The one-line version
Installed by 31 December 2025: claim it, and carry forward what you cannot use. Installed after that date: no federal residential credit, so price the system on its own numbers and check local programmes that still exist. Anyone who tells you otherwise is quoting a rule that has expired.
Sources
- IRS — Residential Clean Energy Credit (credit not available for property placed in service after 31 December 2025; carryforward)
- IRS — FAQs on modifications to sections 25C, 25D, 25E, 30C, 30D, 45L, 45W and 179D under Public Law 119-21
- Congressional Research Service — Expiration and Carryforward Rules for the Residential Clean Energy Credit